Recent Insurance Claim Assistance Projects in Walnut Creek
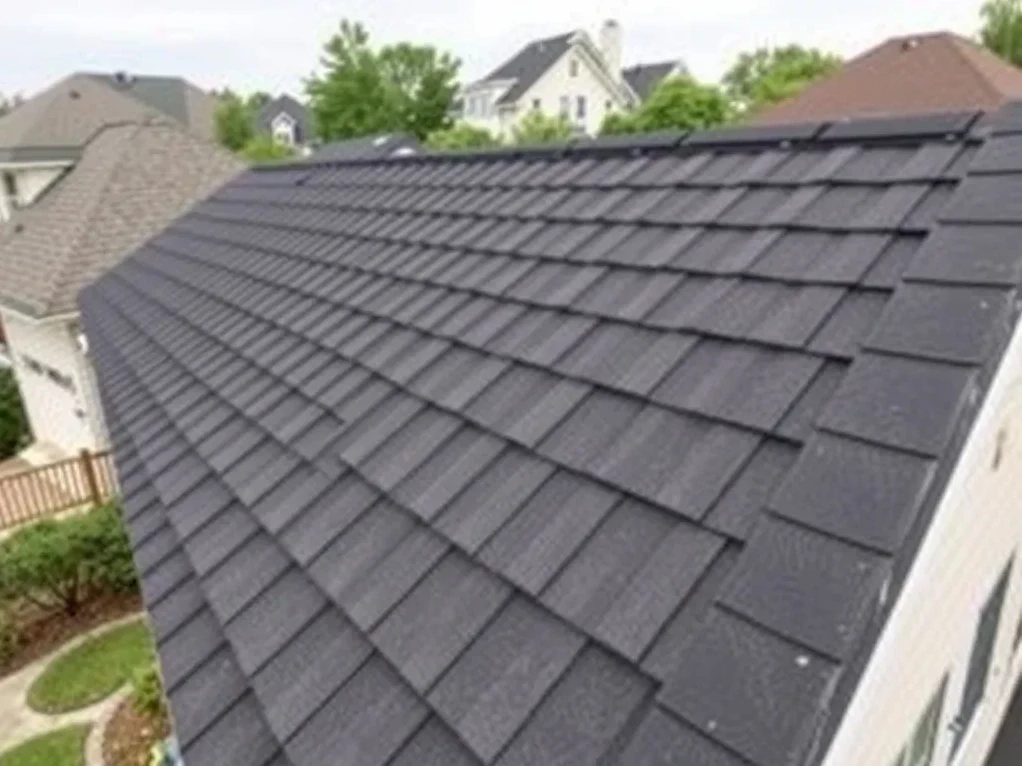
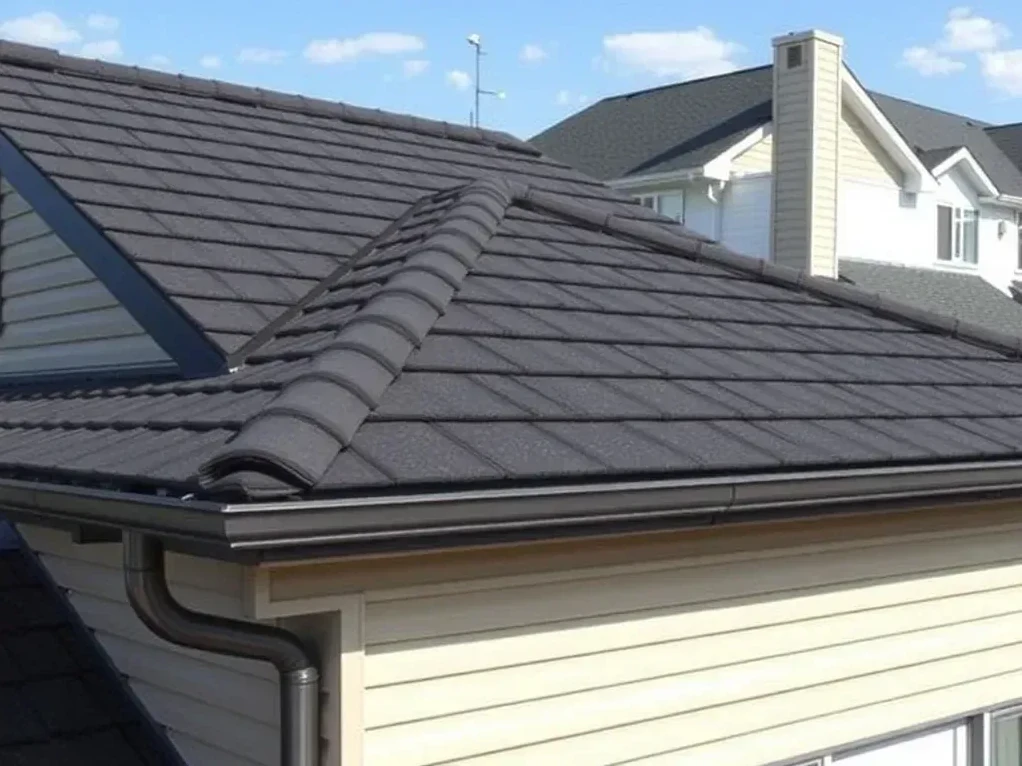
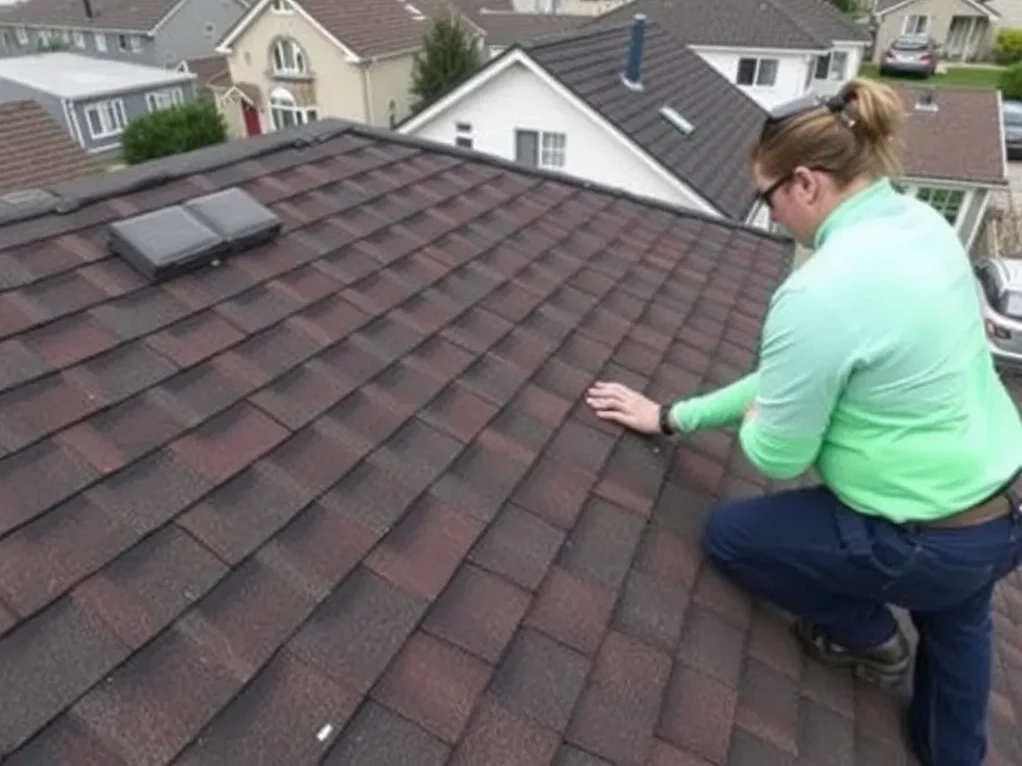
Real work, real roofs — a sample of completed jobs
Walnut Creek Roofers documents storm damage before your insurer ever sees the roof. After a winter storm system or a hail event rolls through, we photograph every bruised shingle, meet your adjuster, and assemble claim documentation that matches your policy coverage. Call 9255031377.
Most claims fail on documentation, not damage. We run a roof inspection that logs granule loss, wind damage, and cracked flashing on a line-item estimate, then photograph the roof deck, sheathing, and every valley with a drone package the adjuster can't dismiss.
A mid-century modern home from the 1960s usually needs a full tear-off and new synthetic underlayment. Spanish and Mediterranean revival homes with clay tile call for ITEL shingle sampling to justify replacement cost rather than a patch.
Depreciation is where homeowners lose money. We file a supplement when the scope of work misses drip edge, ice-and-water shield, or ventilation, and we track proof of loss forms and claim deadlines so nothing expires on your policy coverage.
We are a licensed & insured roofing contractor working across the East Bay, and we treat the claim file with the same care as the roof itself.
Certified installers and a meticulous process from inspection to cleanup.
Top-tier products backed by manufacturer and workmanship warranties.
Built to withstand Walnut Creek's climate for decades of protection.
Insurance claim assistance covers Walnut Creek and the surrounding East Bay, from downtown blocks to hillside homes near Mount Diablo, Las Trampas Regional Wilderness, and Lime Ridge Open Space Preserve.
Real work, real roofs — a sample of completed jobs